Nordea on Pryme – Their Chemical Recycling First Facility Fully Capitalised

Pryme, Quantafuel plastic recycling peer got very positive report by Nordea analyst Elliott Jones. The share price is beaten down since the IPO. Lately market was concerned about the capital raise in the current markets. The capital raise happened, which is a major short term catalyst. The share price saw +30% based on Elliott Jones report. As the major risk is resolved we are bullish. This could be a Pryme ride this year.

If you look at Quantafuel graph, the share price performed very well up to starting the production. Nordea indicates this could happen with Pryme too.

Quatnafuel – we speak to large investors that spoke to the company recently. All the feedback are very positive. Hope for a company update soon.

We are scheduled to talk to Arctic analyst on Quantafuel this week. Stay tuned for a report.

Extracts from Nordea Research:

First facility is fully capitalised

  • What has happened? Capital raise finally complete
    • In the company’s Q4 report in February, Pryme announced that it aimed to raise EUR ~15m to ensure completion of its first facility in Rotterdam
    • On 8 April (last Friday) the raise was finally complete, with Pryme raising NOK 154m via a private placement
    • In line with previous comments, the proceeds will fund remaining capex for its first facility, opex until mid-2023, the acquisition of an industrial plot in the Port of Amsterdam and working capital movements
  • Changes to estimates
    • We include the capital raise terms and expected upcoming repair issue in our model, which results in Pryme’s first facility being fully capitalised (production expected Q4 of this year)
    • The proceeds from the raise result in a slightly smaller future capital requirement than previously expected, with the company’s second facility due in H1 2023 (we build in the raise just prior to construction beginning)
    • We hold all other estimates unchanged
  • Valuation
    • Our valuation methodology unchanged, which involves deriving cashflows for each future facility and discounting back to today (WACC, propability weightings etc all constant)
    • However, by updating our estimates for the above and updating for FX, we arrive at a new target price of NOK 85 (100), primarily due to the dilutive aspect of the capital raise
  • What do we think?
    • Despite the above, we see clear advantages from the completion of the placement:
      • The share price is down by over 35% since the February announcement, pointing to the possibility of a recovery once the dust settles
      • Given a new CEO will start in May and the first oil is expected in six months (key triggers), we foresee no negative changes to business fundamentals
      • Even post the raise, Pryme remains clearly the cheapest option on the market for chemical recyclers today (including 8x lower than QFUEL)
      • Thus we reiterate Buy, with Pryme representing by far the cheapest option by market cap in the chemical recycling space
  • Key triggers?
    • With the raise being our previous immediate trigger, focus for investors should move to development of facility one ahead of production in Q4
    • Key information on this could also be included in the company’s Q1 report on 25 May

We are long Pyme – our family office invested in the capital raise last week.

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.
Brussels Prepares a Ban on Russian Coal Imports – Trading Idea

Brussels has said a block on Russian coal exports will be part of an upcoming fifth sanctions package that is currently being discussed by EU member states.

I just bought JSW, a Polish coal mine.
https://www.jsw.pl/en/investors-relations/presentations-and-webcasts/presentations-and-factsheets/presentations-2021

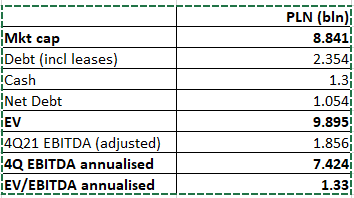
If you take their Q4 and annualize it, you get that the company trades at 1.3 times EV/EBITDA.

The Q4 was good, but did not reflect the coal price moves in Q1.
https://tradingeconomics.com/commodity/coal

Further the coal price in Q4 did not reflected the Russia coal ban.

The stock is very cheap today. If the Russian coal happen this stock could easily triple. It would still trade below 4 EV/EBITDA on Q4 numbers.


Enter your email address to subscribe to this blog and receive notifications of new posts by email.


Disclosure: 
The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action. 

ABG Sundal Collier: The era of gas shipping is here

I wrote here several times about COOL Co. First time when share price was around 75 NOK about five weeks ago. It is 105 today. Today ABG came out with PT of 154NOK. I remain very bullish on COOL for reasons I wrote before.

The era of gas shipping is here
A pure LNG shipping company We believe rates could see all-time highs next winter Initiating coverage with BUY, TP of NOK 154
A pure LNG shipping company
Cool Company Ltd. (CoolCo) is a pure-play LNG shipping company that owns and operates eight TFDE LNG carriers. The company aims to become a leading player in LNG shipping through consolidation opportunities and offering investors pure exposure to the shipping of liquified natural gas. It aims to keep the fleet exposed to the spot market, and to commit to longer-term time charters when prevailing market rates are deemed favourable. Eastern Pacific Shipping and Golar LNG are the two main shareholders, with stakes of 38% and 31%, respectively.

Gas forward curve yield new ATH for LNG rates in ‘23e
Global liquefaction capacity is expected to increase substantially in the coming years and recent events such as the Russian invasion of Ukraine and the EUs acceptance of gas as “sustainable” will likely add even more investments. We expect fleet utilisation above 90% already this year, and as the gas forward curve yields more than USD 1m/day in TCE, we believe rates could hit all-time high next winter. We model for a rate for a 160k TFDE to increase to USD 90k/day in ‘22e, up from an average of USD 87k/day in ’21. Further, we expect the tightening of the LNG shipping market to yield rates of 146k/day in ‘23e and 138k/day in ‘24e, again assuming that European and Asian gas prices remain well above the US price. As such, we model for avg. EBITDA in ’22-‘24e of ~USD 200m, which results in a 36-40% dividend yield in ’23-‘24e.

Initiate with BUY, TP of NOK 154
We initiate our coverage with a target price of NOK 154, derived from a 10% discount to our estimated one-year forward NAV. The forward NAV valuation methodology is based on estimating future asset (vessel) values from forecasted freight rates, which in turn is based on our proprietary supply and demand model. With a limited number of peers in the LNG shipping space, we argue that asset-based valuation is the most applicable pricing method for CoolCo despite modest liquidity in the second-hand market for LNG carriers.

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

COOL – Top Pick on EU Diversification Away from Russian Gas

COOL is one of my top picks to play EU diversification of gas supplies away from Russia. I first wrote here about COOL a month ago when it was trading at 75NOK. It is 95 NOK now. Fearnley says: COOL remains one of the few and best plays on these improving market conditions. They increased their price target from 105NOK to 130 NOK, just three weeks after their initial report. There will be further re-rating. The share price move should remain rapid.

Fearnley Research Summary:

Materializing on Improving LNGC Market
Our take: Likelihood of capitalizing on strengthening fundamentals, revising TP on period market outlook. Reiterate Buy, TP lifted to NOK 130 (NOK 105).
 The LNGC market is playing into the hands of COOL with increasing expectations both for prompt and time-charters as political focus on energy diversification and securing supply intensifies. COOL remains one of the few and best plays on these improving market conditions (see our initiation report March 9th).

We see increased likelihood for COOL to lock in strong earnings for its open positions over the coming months and reiterate our Buy rating while revise our (base case) TP to NOK 130 (Buy, NOK 105 March 29, 2022) reflecting USD 100k/d rates for two open positions in 4q22 (in addition to the USD 120k/d TC previously reported in the market). This underscores the operational leverage and further potential in the platform, while appetite for modern tonnage and rising steel values reduces downside risk.  

Freight rates and operational leverage Period rates for modern vessels continue to improve with TFDEs now quoted at USD 102.5k/d for 1-year durations followed by 3-year duration at USD 85.5k/d. COOL being one of few with open capacity to the improving market could by locking in the two vessels (opening in 4q22) at USD 100k/d generate additional USD 0.4/s EPS for 2023. Given the rumored (TW) 1 year fixture at USD 120k/d and current market assessment, we argue the 100k level to be on likely and on the conservative side.  

Earnings focus over NAV into potential high-cycle We argue NAV lags price development as we head into a potential high-cycle and see earnings as a more appropriate metric to capture current earnings prospects. This is further backed by multi-year charters also seeing strong developments. Rising steel values and limited yard capacity through 2026 (at least at current NB prices) also reduce downside risk together with clear charter preference for modern tonnage. We estimate NAV at NOK 85/sh. and have increased our 2022 EBITDA estimates by 12% and 2023 EBITDA by 18%. Including the two additional TCs we see avg. EPS at USD 2.2/sh over ‘22/’23 which at 7x earnings reflect the NOK 130 TP.  

FEARNLEY SECURITIES ACTED AS JOINT LEAD MANAGER & BOOKRUNNER IN CONNECTION WITH THE EQUITY RAISE AND LISTING OF COOL COMPANY  

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

Quantafuel – Big Day, What´s Next, Brokers Comments

Big day for QFUEL today. Plenty of additional catalysts in the pipeline. Expect wave of broker price target re-ratings. Shorts should be covering. Next two lines modifications should be completed very soon. All four lines should be in operation in Q2. We have been bullish and we are very bullish now.

Terje Eiken, COO of Quantafuel just announced, that he bought 10 000 shares at 21.85 NOK today. Symbolic gesture.

I think there is plenty newsflow in the short term:

  • Short covering
  • Price target changes – Pareto, and Fearnley placed QFUEL price target under review. It means that they may publish PT uplift. Others should follow
  • Completion of modifications on all four lines (within two weeks)
  • Start of the production on all four lines (during Q2)
  • Q1 results – the previous Q4 was the best presentation I saw from QFUEL. We have a high expectations from Q1 call
  • Further announcements on production milestones
  • Strategic partnerships progress

Pareto

QFUEL NO – Quantafuel – Proof of Concept at Skive

Quantafuel announces Proof of Concept (PoC) for its Skive plant, being a key milestone to I) further derisk the technology and to II) move forward with larger-scale Plastic-to-Liquid plants (Quantafuel has a pipeline of more than 5 plants). The company defines PoC as >7 days of continuous production with an uptime above 90% at 16,000 tonnes of annual capacity, with an overall oil yield of 68%. Going forward, the company will continue to remove bottlenecks and optimize operational parameters reaching for higher throughput and earnings, which is a normal exercise in the process industry, according to the company. Quantafuel sates that it will revert with a guiding on Skive in due course, and we also believe new FID announcements are not far away. Today’s news is a strong positive and we expect the share to trade higher after declining ~50% YTD. TP under review.

Fearnley

Quantafuel (Under review)

  • Reached PoC at Skive

QFUEL announce this morning that the company has reached Proof of Concept (PoC) at the chemical recycling plant in Skive, Denmark, after seven days of continuous production on the two operating lines with an uptime above 90%. This corresponds to an annual intake capacity of 16,000 tonnes of plastic waste at plant level (all four lines). Further guiding for the Skive plant will be announced shortly. Going forward, QFUEL will focus on further optimizing operations and removing bottlenecks, moving towards full operation at Skive and next-generation larger-scale facilities. We see this achievement of reaching PoC, after several delays and required upgrades, as an important step towards successful operations at Skive and supportive of the long-term growth plan. Further, we believe this to have a positive effect on investor confidence.

Sparebank

(+) QUANTAFUEL: Announces proof of concept for Skive. The past seven days it has converted 145tonnes which corresponds to an annual production of 16,000t. The achieved proof of concept equals more than 7 days of continuous production with an uptime above 90% and an oil yield of 68%. This implies just short of 11,000 tonnes of output, which QFUEL has previously announced that it will sell for USD1000/t. Hence, Skive will be expected to have an annual turnover of close to NOK100m after this PoC.

ABG Sundal

Quantafuel declares proof-of-concept for Skive

QFUEL (B) announced this morning that it has reached the very important proof-of-concept (PoC) milestone at its Skive chemical recycling plant. This includes continuous operations at >90% utilization for more than seven days at a level corresponding to an annual capacity of 16.000 tonnes of plastic waste feedstock. The oil yield achieved is 68% vs the long-term guidance for its plants which is 80% (which remains). QFUEL states it will continue to optimize parameters and remove bottlenecks to improve throughput and earnings. The milestone means the roll-out plan can continue with even greater confidence. The company will revert with guidance on Skive, but currently our assumptions for gradual ramp-up towards all four lines in operation by Q4 appears reasonable. 

Other trading ideas

  • I wrote about Cibus on Friday. We bought at 220 after the SPO and sold at 232. Good one day trade. It is still a great value, it was 260 last week.
  • I sold out from very recently Norske Skog at 50% over less than a year. I love the company. It is cheap and plent of catalysts. The major fund is out of lock up now. They always sell shortly after lock up expiry. I will buy back on the SPO. It could be this week.
  • We are still bullish on Coolco. We wrote about the company when the share price was around 76 NOK about month ago. It is 96 NOK today. No brainier trade. EU is telling us they will source more gas from other sources than Russia. It means LNG shipping. It is already reflected in the rates. My price target is 130NOK. I believe we could be there within a month
  • I am bullish on Biovica. The story takes longer than I thought, the value is there in my view. Company provided bullish updates last week. Could be one of the best performing positions this year.
  • We are also long other pharma names: Sedana, Bioinvent, Ascelia, Vicore, Hofseth Biocare and Eigr.
  • We remain strongly bullish on Linkfire. They provided very strong guidance at Q4, which the market ignored. Again, this could be one of the best performing stocks this year from my portfolio. There is my article on Linkifre on SeekingAlpha and plenty on this blog.
  • I am long oil through Africa oil, Africa Energy, AkerBP, and Var Energi. Var is out of blackout today. 8 brokers that were in the IPO syndicate should publish their research. Very bullish short term for Var.
  • I am bullish on Aker Horizons. Last week transaction showed, that these guys can deliver. AKH trades at 15% discount to NAV according to Pareto. AKH was caught by the renewable sell off last year. I believe that we are seing a reversal now.
  • I am long Fusion Fuel Green. Similar story like AKH. I expect this to be at least doubling candidate this year.
  • I am also very bullish on Huddly. The management was buying in recent weeks. So we were. Again, this stock should double in next two quarters.

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

Cibus – Trading Idea

Cibus Nordic Real Estate is very solid company with great share price performance.

The company is down 20% in last five days.

The decline was most likely caused by increasing interest rates and probably rumored capital increase. The capital increase happened yesterday after close.

The company announced acquisition of its first property in Denmark and the capital increase is providing funding.

The share is up 1% so far today. I believe the company is well positioned for re-rating. I am long Cibus.

Let´s Brainstorm on Russia/Ukraine

I am looking for ideas how to invest into disruptions caused by the Russia invasion into Ukraine. Any ideas welcome – please place below the article

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

CoolCo – LNG Traffic Jam in Gulf Indicates Share Price Direction

I wrote here several times about CoolCo- a spin off of 8 LNG tankers by Golar. Today, there were two articles that support the story. It is reflected in the share price, which increased to 85 NOK. My price target is 120 NOK.

Soaring LNG Demand Creates Traffic Jam At Gulf Of Mexico Ports

https://www.zerohedge.com/energy/soaring-lng-demand-creates-traffic-jam-gulf-mexico-ports

Germany in talks with Qatar on long-term gas supplies to reduce Russian dependence

Reuters

https://www.reuters.com/world/middle-east/qatar-emir-talks-energy-with-german-minister-emiri-court-2022-03-20/

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

Pareto on CoolCo: An Ofer you should consider

Pareto summary: With energy security becoming the new buzzword after the tragic Ukraine- invasion, modern LNG carriers are set to benefit. CoolCo has already secured one timecharter at a stellar rate since its recent inception – and we expect more to come. Ofer and Trøim have created a vehicle that provides plenty of leverage both operationally and financially – and having traded down since the IPO with initiate coverage with TP of 100 and ~25% upside

My take:
I wrote about CoolCo about two weeks ago. I suggested CoolCo as a qtrading idea for the case situation in Ukraine escalates further and gas supplies get interrupted. This did not happen yet, CoolCo is up only a few % since I wrote about it. I belive the idea still stands. The company is progressing well, charter for usd120k per day was confirmed last week. The company should rerate. And if there is a gas interruption, it will skyrocket. Great risk reward in my view.


Pareto front page summary:

Clean play on TFDE-vessels, plenty of leverage…
With 8x LNGCs built in 2013/14, Golar spin-off CoolCo has most of its fleet exposed to the spot markets in the coming years – and already secured some stellar charters. Focus will be on growth, and we expect accretive transactions to consolidate the fragmented market. The set-up is clean and transparent, with a cash break-even of ~USD 50,000/day and ambition to pay out the ‘majority of free cashflow’ to shareholders. Under our conservative USD 70,000/day market for 2023 this means a yield of ~7% – but clearly room for more.


…to a market that is becoming increasingly political
The LNGC market has seen higher and higher peaks over the past years, with global gas prices continuing their wild swings. The tragic invasion of Ukraine has put European energy security in the spotlight, with the EU targeting a rapid substitution of at least 35mtpa of LNG equivalent. The LNG market is already tight – providing plenty of arbitrage out of the US Gulf – and higher European prices to soak up cargoes from as far as Australia could mean that the current LNGC orderbook goes from a small 2023/24 concern – to not sufficient. The longer-term fundamentals are in any case appealing, with shipyard inflation full orderbooks making us doubt that we will have enough ships for 2025/26 – setting the stage for a true super-cycle. We will see more US export projects sanctioned – projects that are more tonne-mile intensive than others.


BUY TP NOK 100 – bull-case in ‘22/23 adds another NOK 15
We expect COOL to be an active consolidator and grow its fleet substantially in the years to come. Trading above our conservative NAV any ‘ship-for-share’ transaction should be accretive. We find EV/EBITDA 2023e of 6x attractive, with ample upside if more fixtures are secured. Our TP of NOK 100 is derived from a YE’23 NAV, and would increase to NOK 115 if H2’22 – 2023 averages USD 100,000/day, and another NOK 25 if we raise asset values by 10%. CoolCo is the leveraged bet on the near-term LNGC market – a bet we find intriguing given the political and strategic importance of LNG infrastructure now.


Enter your email address to subscribe to this blog and receive notifications of new posts by email.


Disclosure: 
The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

Biovica – CEO video interview on the FDA Requirements

The main quotes from Biovica CEO Anders Rylander 5 minute interview with Redeye Research yesterday are below.

  • We got a very positive FDA feedback in February. That was very positive, because no more issues in the clinical area and only on study that we need to complement.
  • We will redo the study that we have done before. We are already working on it and the May deadline (for FDA response submission) we believe we should be able to meet.
  • We have performed the production of the samples and now we are doing the additional tests the FDA has requested.
  • This is not about new client test. It is about precision test we have done before – this is just in slightly different format with additional samples.
  • We are confident we can reproduce samples we have done in the past
  • We are confident we will meet the deadline
  • This should be the end of FDA review phase. After submission it generally takes 30-60 days for FDA to issue the clearance under normal conditions.

Full interview with Biovica CEO Anders Rylander below: https://www.redeye.se/research/836421/biovica-interview-with-ceo-anders-rylander-video-2?utm_medium=email

Follow up 7 minute interview with Warren Cresswell (President of the Americas, Biovica) with Redeye on lunching DivTum in the USA.

https://www.redeye.se/research/836422/biovica-interview-with-warren-cresswell-president-of-the-americas-video?utm_medium=email

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.

Quantafuel – Back in Operation – Broker Comments

Fearnley Securities: QFUEL announced this morning that repairment of the burner chambers of the two first lines have been completed and tested for production. Both lines have converted plastic waste at a high load after repair completion, and the plant is gradually returning to production.

The timing is in line with QFUEL’s target (announced early February) to resume production in the two lines by mid-March. Going forward, focus remains on increasing uptime and capacity in the production lines to reach Proof-of-Concept.

ABG Sundal Collier:

Quantafuel is back in production on SkiveABG Sundal Collier acted as joint bookrunner in the NOK 400m private placement in Quantafuel
QFUEL (B) announced this morning that it has completed the repair work for the first two production lines in Skive. Both lines have been tested in production and have converted plastics at high load after the repair. The plant is gradually returning to production now. This is in line with the comments from the Q4 report end February where it stated that both lines were expected operational by mid-March. It is positive to see that Skive is now operational.

Note on valuation

Before the announcement on the production interruption QFUEL traded above 25 NOK. On the announcement it went down to around 15 NOK. Today the stock gained back to 20 NOK. We are still 20% below the announcement.

When the market believed that Proof of Concept is eminent, the stock was trading close to 80 NOK. Based on all the conversations we had we believe that the proof of concept is at max weeks away. There is plenty of upside.

Enter your email address to subscribe to this blog and receive notifications of new posts by email.

Disclosure: 

The goal of the blog is to provide investment ideas for further research. I/we have a beneficial position in the shares discussed above either through stock ownership, options, or other derivatives. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it. I have no business relationship with any company whose stock is mentioned in this article. The article does not represent investment advice. Please do your own research before making any investment action.